Maximize 401(k) 2026: Advanced Strategies for 15% Higher Returns
Anúncios
Maximizing Your 401(k) in 2026: Advanced Contribution Strategies for a 15% Higher Return
Retirement planning is a journey that requires foresight, discipline, and a strategic approach. For many, the 401(k) serves as the cornerstone of their retirement savings. While the basic principles of contributing regularly and investing wisely are well-known, achieving a significant boost – say, a 15% higher return – requires delving into 401k advanced strategies. As we look towards 2026, understanding and implementing these sophisticated tactics can make a profound difference in the size and security of your golden years.
The financial landscape is ever-evolving, and what worked a decade ago might not be the most optimal path today. Inflation, market volatility, and changing tax laws necessitate a dynamic approach to retirement savings. This comprehensive guide will explore advanced 401(k) strategies tailored for the discerning investor, aiming to help you not just meet your retirement goals, but exceed them by a substantial margin. We’ll move beyond simple contributions and explore nuances that can unlock significant growth potential.
Anúncios
Understanding your 401(k) is more than just knowing your contribution limit. It’s about leveraging every available rule and option to your advantage. From understanding the nuances of employer matching to navigating complex investment choices, every decision can impact your long-term wealth. This article will equip you with the knowledge to make those decisions confidently, ensuring your 401(k) is working as hard as possible for you.
Anúncios
Understanding the Foundation: Beyond Basic Contributions
Before diving into the more intricate 401k advanced strategies, it’s crucial to ensure you have the basics mastered. Maximizing your employer match is paramount. This is essentially “free money” and neglecting it is akin to leaving a significant portion of your salary on the table. Many employers offer a match up to a certain percentage of your salary, and contributing at least that much should be your absolute minimum.
Beyond the match, consistently contributing the maximum allowable amount to your 401(k) is the next fundamental step. For 2026, while specific limits are yet to be announced, they are likely to increase from previous years due to inflation adjustments. Staying informed about these limits and adjusting your contributions accordingly is vital. This ensures you’re taking full advantage of the tax-deferred growth your 401(k) offers.
However, simply contributing the maximum isn’t enough to achieve a 15% higher return. The real magic happens when you combine consistent, maximum contributions with astute investment choices and advanced tactical maneuvers. It’s about optimizing every facet of your 401(k) – from contribution methods to asset allocation – to create a powerful engine for wealth accumulation.
Advanced Strategy 1: The Power of Catch-Up Contributions
For those aged 50 and over, catch-up contributions are one of the most effective 401k advanced strategies. The IRS allows individuals in this age bracket to contribute an additional amount beyond the standard limit. This provision is specifically designed to help older workers boost their retirement savings as they approach their golden years, often when their earning potential is at its peak.
The impact of catch-up contributions cannot be overstated. Consider an individual who consistently contributes the maximum standard amount for years. Upon turning 50, adding an extra several thousand dollars annually can significantly accelerate their savings. Over a decade, these additional contributions, compounded with market returns, can amount to a substantial sum, potentially contributing a large portion to that desired 15% higher return.
It’s not just about the raw amount; it’s about the compounding effect. The earlier you start making catch-up contributions after turning 50, the longer that extra money has to grow tax-deferred. This strategy is particularly powerful for those who may have started saving later in life or who want to aggressively build their nest egg in their final working years. Ensure you are aware of the specific catch-up contribution limits for 2026 and adjust your payroll deductions accordingly.
Advanced Strategy 2: Mastering the Mega Backdoor Roth
The Mega Backdoor Roth is perhaps one of the most sophisticated 401k advanced strategies, allowing high-income earners to contribute significantly more to a Roth account than the standard Roth IRA limits permit. This strategy is not available to everyone; it requires your employer’s 401(k) plan to allow after-tax non-Roth contributions and in-service distributions or rollovers.
Here’s how it generally works: You contribute after-tax money to your 401(k) beyond the pre-tax and Roth 401(k) limits, up to the overall IRS maximum for combined employer and employee contributions. Once these after-tax funds are in your 401(k), you then convert or roll them over into a Roth IRA. The beauty of this strategy is that future growth on these converted funds is tax-free in retirement, just like a traditional Roth IRA.
The Mega Backdoor Roth can be a game-changer for those looking to build a substantial tax-free retirement income stream. It circumvents the income limitations typically associated with direct Roth IRA contributions. While it requires careful execution and understanding of your specific plan’s rules, the long-term benefits of tax-free growth and withdrawals can significantly enhance your retirement portfolio, potentially contributing a substantial portion to the 15% higher return goal. Consult with your plan administrator and a financial advisor to determine if this strategy is available and suitable for your situation.
Advanced Strategy 3: Strategic Asset Allocation and Rebalancing
Beyond how much you contribute, how you invest those contributions within your 401(k) is equally, if not more, critical for achieving higher returns. This is where strategic asset allocation and regular rebalancing come into play as crucial 401k advanced strategies.
Asset allocation refers to how you divide your investments among different asset classes, such as stocks, bonds, and cash equivalents. A common misconception is that a “set-it-and-forget-it” approach to investment allocation is sufficient. However, market conditions change, and your risk tolerance evolves over time. A truly advanced strategy involves actively managing your asset allocation to align with your financial goals, time horizon, and risk profile.
For younger investors with a long time horizon, a more aggressive allocation heavily weighted towards equities might be appropriate to maximize growth potential. As you approach retirement, gradually shifting towards a more conservative mix with a higher proportion of bonds can help preserve capital. However, even within these general guidelines, opportunities exist to optimize. For example, considering global diversification, small-cap vs. large-cap exposure, and sector-specific investments can further refine your portfolio.
Rebalancing is the practice of adjusting your portfolio periodically to maintain your desired asset allocation. Market fluctuations can cause your portfolio to drift from its original target – for instance, a strong bull market might cause your equity allocation to grow beyond your target percentage. Rebalancing involves selling off some of your overperforming assets and buying more of your underperforming ones, bringing your portfolio back into alignment. This disciplined approach helps manage risk and can capitalize on market movements by “buying low and selling high” in a structured manner.
Advanced Strategy 4: Optimizing Investment Choices within Your 401(k)
Many 401(k) plans offer a bewildering array of investment options. Simply picking a target-date fund or a broad market index fund might be a good starting point, but optimizing your choices can be a powerful 401k advanced strategy for higher returns. This involves a deeper dive into the specific funds available to you.
Evaluating Fund Expenses:
One of the most significant detractors from long-term returns is high expense ratios. Even seemingly small fees, compounded over decades, can erode a substantial portion of your gains. Always prioritize funds with low expense ratios, such as passively managed index funds or exchange-traded funds (ETFs) if available within your plan. A difference of even 0.5% in annual fees can translate into tens of thousands of dollars over a 30-year investment horizon.
Understanding Fund Performance and Holdings:
While past performance is not indicative of future results, understanding a fund’s historical performance relative to its benchmark and peers can provide valuable insights. More importantly, examine the fund’s underlying holdings. Are you comfortable with the companies or sectors it invests in? Does it align with your overall investment philosophy and risk tolerance?
Diversification Beyond Broad Indexes:
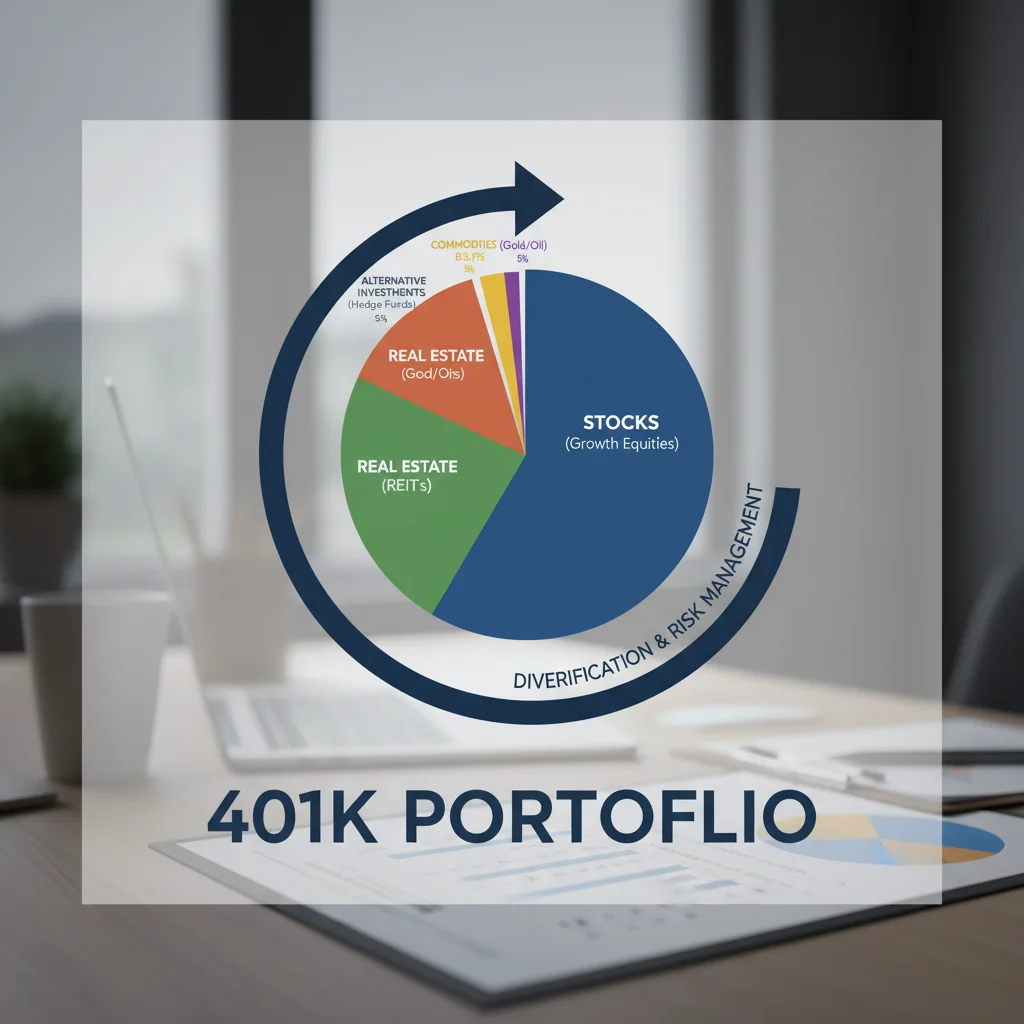
While broad market index funds offer excellent diversification, consider if your plan allows for more granular exposure. For example, if your plan offers international stock funds, bond funds with varying durations, or even real estate investment trusts (REITs), integrating these can further diversify your portfolio and potentially enhance returns by capturing growth from different market segments.
Remember, the goal is not to chase the hottest trend but to build a robust, diversified portfolio that aligns with your long-term objectives and minimizes unnecessary costs. Regularly review your fund choices, at least annually, to ensure they continue to meet your needs and perform as expected.
Advanced Strategy 5: Leveraging the Roth 401(k) Option
For those who anticipate being in a higher tax bracket in retirement than they are today, the Roth 401(k) option is a powerful 401k advanced strategy. Unlike a traditional 401(k) where contributions are pre-tax and withdrawals are taxed in retirement, Roth 401(k) contributions are made with after-tax dollars. The significant advantage? Qualified withdrawals in retirement are completely tax-free.
The Roth 401(k) offers several compelling benefits:
- Tax-Free Growth and Withdrawals: This is the primary allure. All earnings grow tax-free, and distributions in retirement are also tax-free, provided you meet certain conditions (age 59½ and the account has been open for at least five years). This can be immensely valuable, especially as tax rates are unpredictable in the future.
- No Income Limitations: Unlike a Roth IRA, there are no income limitations to contribute to a Roth 401(k). This makes it an accessible option for high-income earners who are otherwise phased out of direct Roth IRA contributions.
- Flexibility: Some plans allow you to split your contributions between traditional and Roth 401(k)s, offering a hybrid approach that can provide tax diversification in retirement.
Deciding between a traditional and Roth 401(k) hinges on your current tax bracket versus your anticipated tax bracket in retirement. If you believe your taxes will be higher in the future, a Roth 401(k) is an excellent choice. If you expect to be in a lower bracket, the immediate tax deduction of a traditional 401(k) might be more appealing. For many, a balanced approach using both can provide optimal tax flexibility in retirement.
Advanced Strategy 6: Understanding and Utilizing In-Service Withdrawals/Rollovers
For some, the investment options within their current 401(k) plan may be limited or have high fees. This is where understanding in-service withdrawals or rollovers becomes a critical 401k advanced strategy. An in-service withdrawal allows you to move a portion of your 401(k) funds to an IRA (either traditional or Roth, depending on the type of funds) while still employed and contributing to your 401(k).
This strategy offers several advantages:
- Expanded Investment Options: IRAs typically offer a much wider array of investment choices compared to employer-sponsored 401(k)s. This can allow you to invest in funds with lower fees, better performance, or more specialized asset classes not available in your 401(k).
- Lower Fees: You might find lower-cost investment options in an IRA, which can significantly boost your net returns over time.
- Consolidation: If you have multiple old 401(k)s from previous employers, consolidating them into a single IRA can simplify your financial life and make managing your investments easier.
It’s crucial to check with your plan administrator to see if your 401(k) allows for in-service withdrawals. Not all plans do, and there might be specific rules regarding the age at which you can do this or the type of funds that can be rolled over (e.g., only after-tax contributions). If your plan permits it, this can be a powerful tool for taking greater control over your investment portfolio and optimizing for higher returns.
Advanced Strategy 7: Tax-Loss Harvesting within Your Investment Portfolio (Outside 401(k) but Related)
While tax-loss harvesting cannot be directly performed within a tax-advantaged account like a 401(k), understanding its principles and applying it to your taxable brokerage accounts can indirectly enhance your overall retirement savings strategy. This is a complementary 401k advanced strategy that optimizes your entire investment ecosystem.
Tax-loss harvesting involves selling investments at a loss to offset capital gains and, potentially, a limited amount of ordinary income. For example, if you have realized capital gains from selling other investments, you can use investment losses to reduce or even eliminate those gains. If your losses exceed your gains, you can deduct up to $3,000 of those losses against your ordinary income in a given year, carrying forward any remaining losses to future years.
How does this relate to your 401(k)? By reducing your current tax liability through tax-loss harvesting in your taxable accounts, you effectively free up more capital that can be directed towards your 401(k) or other retirement vehicles. This allows you to accelerate your contributions, take advantage of employer matches, or simply have more funds available for investment, all contributing to your overall wealth accumulation and the goal of a 15% higher return across your financial portfolio.
Advanced Strategy 8: Considering a Self-Directed 401(k)
For entrepreneurs, small business owners, or those with specific investment needs, a self-directed 401(k) (also known as an individual 401(k) or solo 401(k)) can be an incredibly powerful 401k advanced strategy. This type of plan is designed for individuals with self-employment income, even if it’s a side gig. It allows for significantly higher contribution limits than a traditional 401(k) or IRA, as you can contribute both as an employee and as an employer.
The primary advantage of a self-directed 401(k) is the expanded investment flexibility. Unlike typical employer-sponsored plans, a self-directed 401(k) can allow you to invest in a much broader range of assets, including:
- Individual stocks and bonds
- Mutual funds and ETFs (beyond what a standard 401(k) offers)
- Real estate (residential, commercial, undeveloped land)
- Private equity and venture capital
- Precious metals
This increased control over investment choices can be instrumental in seeking higher returns, especially if you have expertise in specific alternative asset classes or want to tailor your portfolio more precisely. The ability to act as both employee and employer allows for substantial contributions, potentially reaching close to $69,000 in 2024 (this limit is adjusted annually for inflation), significantly accelerating your retirement savings.
However, it comes with increased administrative responsibilities and requires a deeper understanding of prohibited transactions and IRS rules to avoid penalties. If you qualify and are comfortable with the added complexity, a self-directed 401(k) can be a cornerstone of your 401k advanced strategies for maximizing retirement wealth.
The Importance of Professional Guidance
While this guide outlines several 401k advanced strategies, the world of retirement planning is complex and highly individualized. Market conditions, tax laws, and personal financial situations are constantly changing. Therefore, seeking professional financial advice is not just recommended but often essential for optimizing your 401(k) and achieving your specific financial goals.
A qualified financial advisor can help you:
- Assess Your Current Situation: They can analyze your income, expenses, existing investments, and risk tolerance to create a personalized retirement plan.
- Navigate Complex Rules: Strategies like the Mega Backdoor Roth or self-directed 401(k)s have specific IRS rules and requirements. An advisor can ensure you comply and avoid costly mistakes.
- Optimize Asset Allocation: They can help you craft an investment portfolio within your 401(k) that is diversified, cost-effective, and aligned with your time horizon and risk profile.
- Stay Updated on Tax Law Changes: Tax laws related to retirement accounts can change annually. An advisor stays abreast of these changes and can adjust your strategy accordingly.
- Provide Ongoing Support: Retirement planning isn’t a one-time event. An advisor can provide ongoing guidance, help you rebalance your portfolio, and make adjustments as your life circumstances evolve.
The cost of professional advice is often outweighed by the value it provides in terms of optimized returns, tax efficiency, and peace of mind. Consider it an investment in your future, contributing significantly to your goal of a 15% higher return on your 401(k) investments.
Conclusion: A Proactive Approach to Your Retirement Future
Achieving a 15% higher return on your 401(k) by 2026 is an ambitious yet attainable goal when you employ 401k advanced strategies. It moves beyond simply contributing and involves a proactive, informed, and strategic approach to every aspect of your retirement savings.
From maximizing employer matches and leveraging catch-up contributions to mastering sophisticated techniques like the Mega Backdoor Roth and strategic asset allocation, each strategy plays a vital role. Optimizing your investment choices within your plan, understanding the benefits of a Roth 401(k), and considering in-service rollovers or even a self-directed 401(k) can collectively transform your retirement trajectory.
The key takeaway is that your 401(k) is a powerful tool, but its full potential is only unlocked through diligent management and the application of advanced financial principles. By implementing these strategies and, where necessary, seeking expert guidance, you are not just saving for retirement; you are actively building a more prosperous and secure future. Start today, stay informed, and watch your retirement nest egg grow significantly beyond conventional expectations.