Decoding Inflation Trends: Protect Your Portfolio from 4% Annual Decline by 2026
Anúncios
Decoding the Current Inflation Trends: How to Protect Your Portfolio from a 4% Annual Decline in 2026
The global economy is a dynamic and often unpredictable entity, constantly influenced by a myriad of factors. Among these, inflation stands out as a particularly formidable force, capable of eroding purchasing power and diminishing the real value of investments. As we look towards 2026, many financial experts and economists are projecting a continued, albeit potentially fluctuating, inflationary environment. Understanding these inflation trends and their potential impact on your investment portfolio is not just prudent; it’s essential for safeguarding your financial future. This comprehensive guide will delve into the intricacies of current inflation, explore its potential trajectory, and, most importantly, equip you with actionable strategies to protect your portfolio from a projected 4% annual decline by 2026.
Anúncios
Understanding the Current Inflation Landscape
Before we can protect our assets, we must first understand the enemy. Inflation, in its simplest form, is the rate at which the general level of prices for goods and services is rising, and subsequently, the purchasing power of currency is falling. The past few years have witnessed significant inflationary pressures, driven by a confluence of factors including supply chain disruptions, unprecedented fiscal and monetary stimulus, geopolitical tensions, and shifts in consumer demand. While central banks have begun to tighten monetary policy to combat these pressures, the effects are not immediate, and the underlying structural issues contributing to inflation may persist.
Key Drivers of Recent Inflation
- Supply Chain Bottlenecks: The COVID-19 pandemic exposed vulnerabilities in global supply chains, leading to shortages and increased costs for raw materials and finished goods.
- Fiscal and Monetary Stimulus: Governments and central banks injected massive amounts of liquidity into economies to mitigate the economic impact of the pandemic, leading to an abundance of money chasing fewer goods.
- Geopolitical Events: Conflicts and trade disputes can disrupt commodity markets, particularly energy and food, leading to price spikes.
- Labor Market Dynamics: Tight labor markets and rising wage demands can contribute to inflationary pressures as businesses pass on higher labor costs to consumers.
- Consumer Demand Shifts: A shift in consumer spending from services to goods during the pandemic further exacerbated supply chain issues and drove up prices.
These drivers have created a complex inflationary environment that is unlikely to dissipate entirely in the short term. While headline inflation figures might fluctuate, the underlying trend suggests a sustained need for vigilance.
Anúncios
The Projected 4% Annual Decline by 2026: What Does it Mean?
When we talk about a ‘4% annual decline’ due to inflation, it’s crucial to clarify what this implies. It doesn’t necessarily mean your portfolio will literally shrink by 4% in nominal terms. Instead, it refers to a 4% reduction in the real purchasing power of your investments each year if they do not keep pace with inflation. For instance, if your portfolio grows by 3% in a year, but inflation is 4%, your real return is actually -1%. Over several years, this seemingly small annual erosion can significantly impact your long-term financial goals.
The Compounding Effect of Inflation
The danger of inflation lies in its compounding nature. A consistent 4% annual decline in purchasing power means that an investment worth $100,000 today would effectively be worth only about $88,475 in terms of purchasing power by 2026, assuming a continuous 4% inflation rate and no nominal growth. This erosion can derail retirement plans, reduce the value of savings, and make future financial aspirations harder to achieve. Therefore, strategies to combat this inflation portfolio protection are not just about seeking high nominal returns, but about achieving returns that outpace inflation.
Strategies for Inflation Portfolio Protection
Protecting your portfolio from inflation requires a multi-faceted approach, focusing on asset classes that historically perform well during periods of rising prices, and adopting strategies that prioritize real returns. Here are some key strategies to consider:
1. Diversify Your Assets Strategically
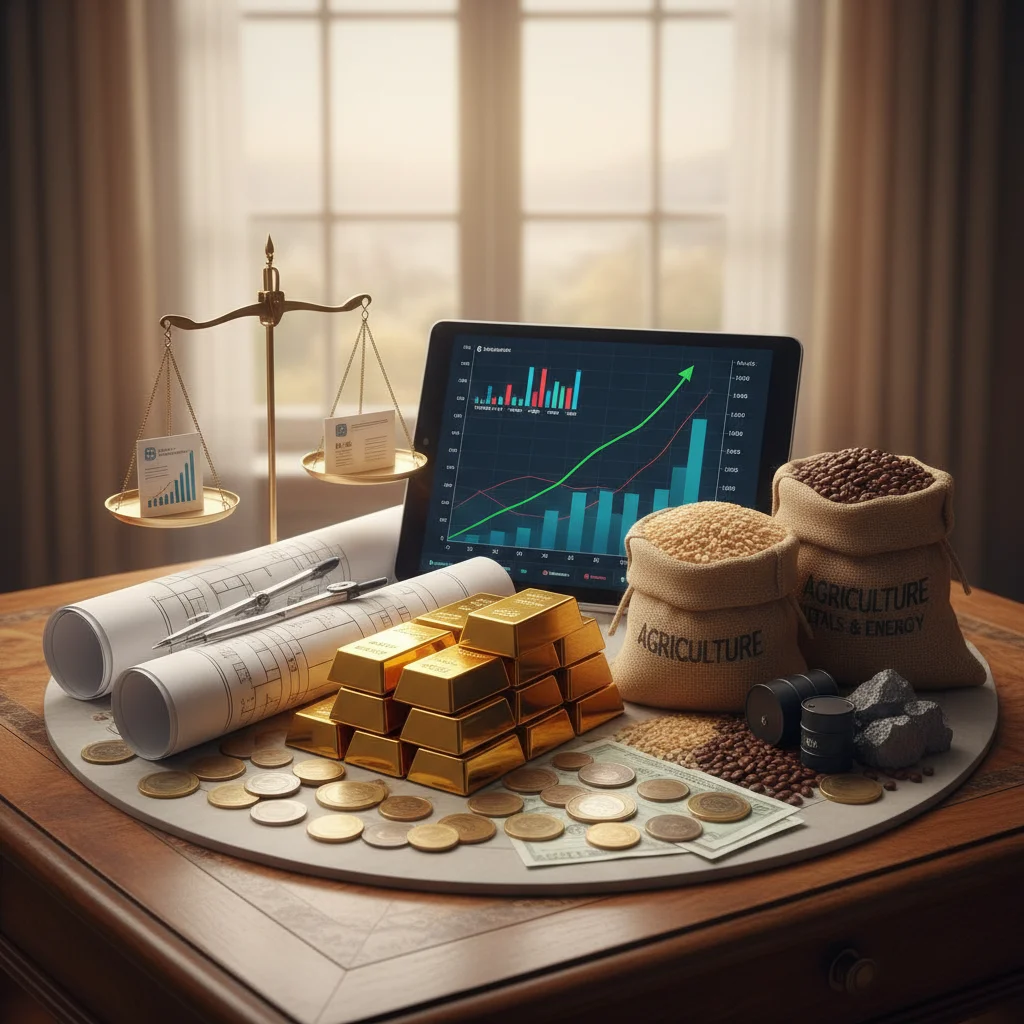
Diversification is always a cornerstone of sound investment, but in an inflationary environment, it becomes even more critical. Certain asset classes tend to offer better inflation hedges than others. A well-diversified portfolio for inflation protection might include:
- Real Estate: Historically, real estate has been a strong inflation hedge. Property values and rental income tend to rise with inflation, providing a natural buffer against rising prices. This can include direct ownership, Real Estate Investment Trusts (REITs), or real estate funds.
- Commodities: Raw materials like gold, silver, oil, and agricultural products often see their prices increase during inflationary periods. Gold, in particular, is often considered a traditional safe haven.
- Treasury Inflation-Protected Securities (TIPS): These are government bonds whose principal value adjusts with inflation, as measured by the Consumer Price Index (CPI). They offer a guaranteed real return, making them a direct hedge against inflation.
- Value Stocks: While growth stocks can suffer as interest rates rise to combat inflation, value stocks – companies with strong fundamentals, stable earnings, and often paying dividends – can be more resilient. Their intrinsic value may be less sensitive to market sentiment shifts caused by inflation fears.
- Infrastructure Investments: Assets like toll roads, utilities, and communication networks often have pricing power and long-term contracts that are indexed to inflation, making them attractive during inflationary times.
2. Consider Inflation-Indexed Investments
Beyond TIPS, other inflation-indexed investments can provide direct protection. These include:
- Inflation-Indexed Annuities: Some annuities offer payments that adjust with inflation, ensuring your future income maintains its purchasing power.
- Floating-Rate Securities: These bonds have interest rates that reset periodically based on a benchmark rate, which often rises during inflationary periods. This helps their yield keep pace with inflation.
3. Focus on Companies with Pricing Power
In an inflationary environment, businesses that can pass on increased costs to consumers without significantly impacting demand are particularly attractive. These companies often possess strong brand loyalty, unique products or services, or operate in essential industries. Look for:
- Consumer Staples: Companies producing goods people need regardless of the economic climate (e.g., food, beverages, household products).
- Healthcare: Demand for healthcare services tends to be inelastic.
- Utilities: Often regulated and able to adjust rates, though subject to regulatory approval.
- Technology Companies with Strong Moats: Companies with dominant market positions or proprietary technology can often maintain pricing power.
4. Re-evaluate Your Bond Holdings
Traditional fixed-income investments, particularly long-duration bonds, are generally vulnerable to inflation. As inflation rises, interest rates typically follow, which can depress the value of existing bonds with lower fixed yields. Consider:
- Shorter-Duration Bonds: These are less sensitive to interest rate changes.
- Bond Ladders: A strategy where you invest in bonds with staggered maturity dates, allowing you to reinvest maturing bonds at potentially higher rates.
- High-Yield Bonds (with caution): While offering higher returns, they also carry greater credit risk. Careful selection is paramount.
5. Alternative Investments
Beyond traditional stocks and bonds, alternative investments can offer unique inflation-hedging properties:
- Private Equity/Debt: Direct investments in private companies or loans can sometimes offer higher returns and less correlation with public markets.
- Hedge Funds: Certain hedge fund strategies are designed to perform well in various market conditions, including inflationary ones. However, these are often illiquid and come with higher fees.
- Collectibles: Art, rare coins, stamps, and other collectibles can retain or increase their value during inflationary periods, though they are highly illiquid and subject to individual market demand.
Practical Steps for Implementing Inflation Protection Strategies
Implementing these strategies requires more than just understanding them; it demands careful planning and execution. Here’s a step-by-step approach:
Step 1: Assess Your Current Portfolio and Risk Tolerance
Before making any changes, thoroughly review your existing portfolio. Understand your current asset allocation, identify your exposure to inflation-sensitive assets, and, most importantly, honestly assess your risk tolerance. An aggressive investor might lean more towards commodities and real estate, while a conservative investor might prioritize TIPS and inflation-indexed annuities.
Step 2: Consult a Financial Advisor
Navigating an inflationary environment can be complex. A qualified financial advisor can provide personalized guidance, help you understand the nuances of various inflation-hedging strategies, and ensure your investment decisions align with your broader financial goals and risk profile. They can also help you avoid common pitfalls and emotional decision-making.
Step 3: Gradually Adjust Your Asset Allocation
Avoid making drastic, sudden changes to your portfolio. Instead, gradually rebalance your asset allocation to incorporate more inflation-resilient assets. This systematic approach helps mitigate market timing risks and allows you to adapt to evolving economic conditions.
Step 4: Stay Informed and Monitor Economic Indicators
The economic landscape is constantly shifting. Stay abreast of key economic indicators such as the Consumer Price Index (CPI), Producer Price Index (PPI), interest rate announcements from central banks, and global geopolitical developments. This vigilance will enable you to make timely adjustments to your strategy.
Step 5: Focus on Long-Term Goals, Not Short-Term Noise
While the prospect of a 4% annual decline in purchasing power can be concerning, it’s crucial to maintain a long-term perspective. Short-term market fluctuations and economic headlines can be distracting. Stick to your well-thought-out inflation portfolio protection plan, and remember that consistent, disciplined investing often yields the best results over time.
Beyond Investments: Personal Finance Strategies to Combat Inflation
While investment strategies are paramount, personal finance decisions also play a significant role in mitigating the impact of inflation. These complementary strategies can bolster your overall financial resilience:
1. Manage Debt Wisely
In an inflationary environment, fixed-rate debt (like a traditional mortgage) can become less burdensome over time as the real value of your payments decreases. However, variable-rate debt (like some credit cards or lines of credit) can become more expensive as interest rates rise to combat inflation. Prioritize paying down high-interest, variable-rate debt.
2. Increase Your Income Streams
Seeking opportunities to increase your income, whether through salary negotiations, a side hustle, or skill development, can help you keep pace with rising costs. The more disposable income you have, the better equipped you are to absorb inflationary pressures.
3. Control Discretionary Spending
Review your budget and identify areas where you can reduce discretionary spending. While not a direct investment strategy, freeing up cash flow allows you to save more, invest more, or pay down debt, all of which contribute to stronger financial health in an inflationary environment.
4. Build an Emergency Fund
An adequate emergency fund (typically 3-6 months of living expenses) is always crucial, but especially so during times of economic uncertainty and inflation. It provides a buffer against unexpected expenses, preventing you from having to sell investments at inopportune times or take on high-interest debt.
5. Invest in Yourself (Human Capital)
Enhancing your skills and education can increase your earning potential, which is a powerful hedge against inflation. The ability to command a higher salary means your income can keep pace with or even outstrip rising prices.
Potential Risks and Considerations
While these strategies offer robust inflation portfolio protection, it’s important to acknowledge potential risks and considerations:
- Market Volatility: Inflationary periods can often be accompanied by increased market volatility. Be prepared for fluctuations and avoid panic selling.
- Interest Rate Risk: As central banks raise interest rates to combat inflation, this can negatively impact certain asset classes, particularly long-duration bonds and some growth stocks.
- Liquidity Risk: Some inflation-hedging assets, like real estate or certain alternative investments, can be illiquid, meaning they are not easily converted to cash.
- Over-Hedging: While important to protect against inflation, over-allocating to inflation-sensitive assets could lead to underperformance if inflation subsides more quickly than expected. Balance is key.
- Forecasting Uncertainty: Economic forecasts, including inflation projections, are inherently uncertain. Remain flexible and be willing to adjust your strategy as new information becomes available.
The goal is not to eliminate all risk, but to manage it intelligently and construct a portfolio that is resilient across various economic scenarios.
Conclusion: Proactive Measures for a Resilient Portfolio
The prospect of a 4% annual decline in purchasing power by 2026 due to inflation is a significant concern for investors. However, by understanding the drivers of inflation and implementing proactive, well-thought-out strategies, you can significantly mitigate its impact on your investment portfolio. Strategic diversification, a focus on inflation-indexed assets and companies with pricing power, and a commitment to continuous learning are your strongest allies.
Remember, protecting your wealth in an inflationary environment is an ongoing process, not a one-time fix. Regularly review your portfolio, consult with financial professionals, and adapt your strategies as economic conditions evolve. By taking these decisive steps, you can build a more resilient portfolio, safeguard your purchasing power, and stay firmly on track to achieve your long-term financial aspirations, even in the face of persistent inflation. Your financial future depends on these informed decisions today.